
Business Owners Policy
Property and general liability bundled into one policy for small and mid-sized firms.
Read more →Business Insurance
Vehicles owned, hired or driven by employees on company business.
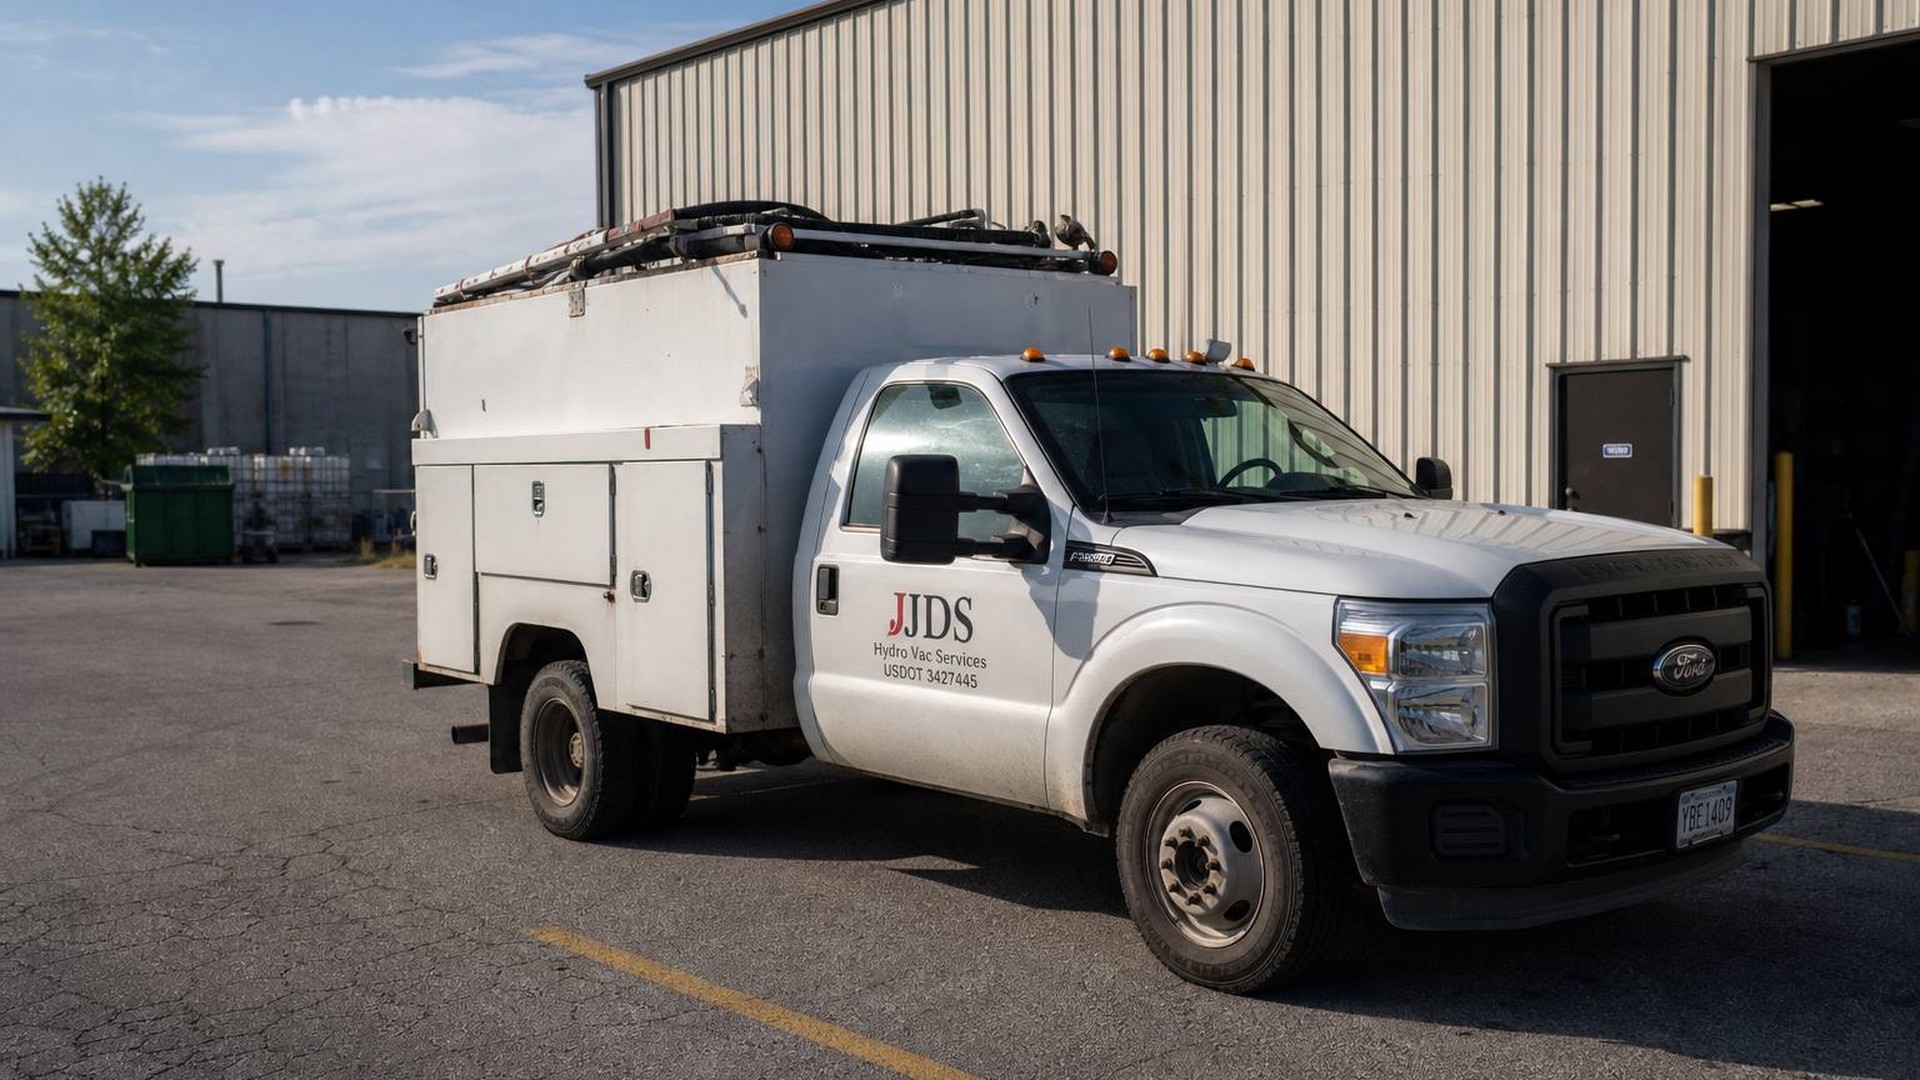
A personal auto policy excludes business use, which leaves a gap that only appears after an accident. Commercial auto covers company vehicles, and the hired and non-owned extension covers rentals and employees driving their own cars on your behalf.
Questions
Yes. Their personal policy responds first, but claims above its limit come back to the business. Non-owned auto liability is the cover for that and it is inexpensive.
Commuting is usually fine. Deliveries, client visits in a signed vehicle and carrying goods for hire are generally excluded.
Often taken together
Property and general liability bundled into one policy for small and mid-sized firms.
Read more →
Third-party injury, property damage and advertising injury claims against your business.
Read more →Tell us what you already have and we will show you where this fits — or tell you plainly that you do not need it.