
Business Owners Policy
Property and general liability bundled into one policy for small and mid-sized firms.
Read more →Business Insurance
Medical care and wage replacement for employees injured at work.
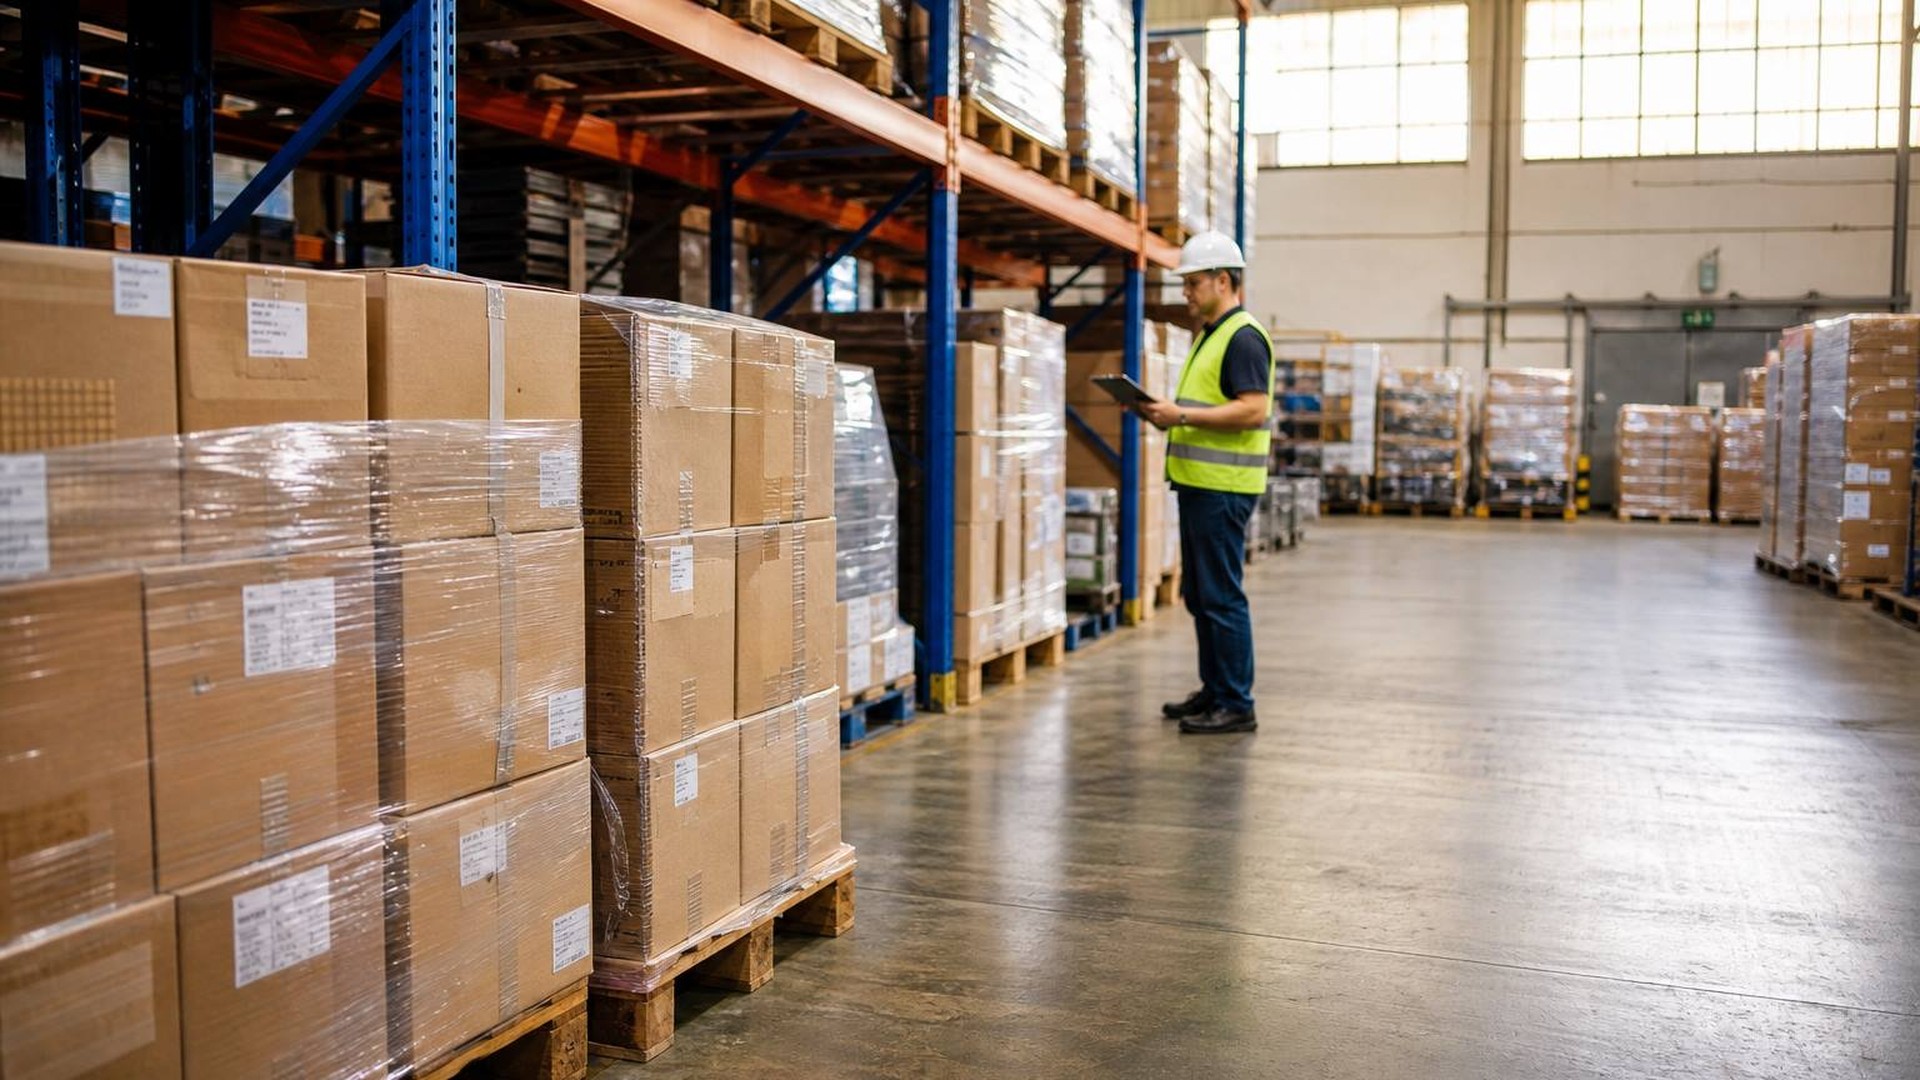
Workers compensation is mandatory in nearly every state once you have employees, with rules and penalties that vary by state. It pays an injured employee’s medical costs and a share of lost wages, and in exchange limits the employer’s exposure to being sued over the injury.
Questions
Sometimes. Several states treat uninsured subcontractors as your employees for premium and claims purposes. Collecting certificates from every sub is what keeps that from becoming your problem at audit.
A factor comparing your claims history to firms of similar type and size. Below 1.0 reduces premium, above increases it. It is also used as a prequalification screen on many contracts.
Often taken together
Property and general liability bundled into one policy for small and mid-sized firms.
Read more →Third-party injury, property damage and advertising injury claims against your business.
Read more →
Buildings, contents, stock and equipment against fire, theft and weather.
Read more →Tell us what you already have and we will show you where this fits — or tell you plainly that you do not need it.