
Business Owners Policy
Property and general liability bundled into one policy for small and mid-sized firms.
Read more →Business Insurance
Buildings, contents, stock and equipment against fire, theft and weather.
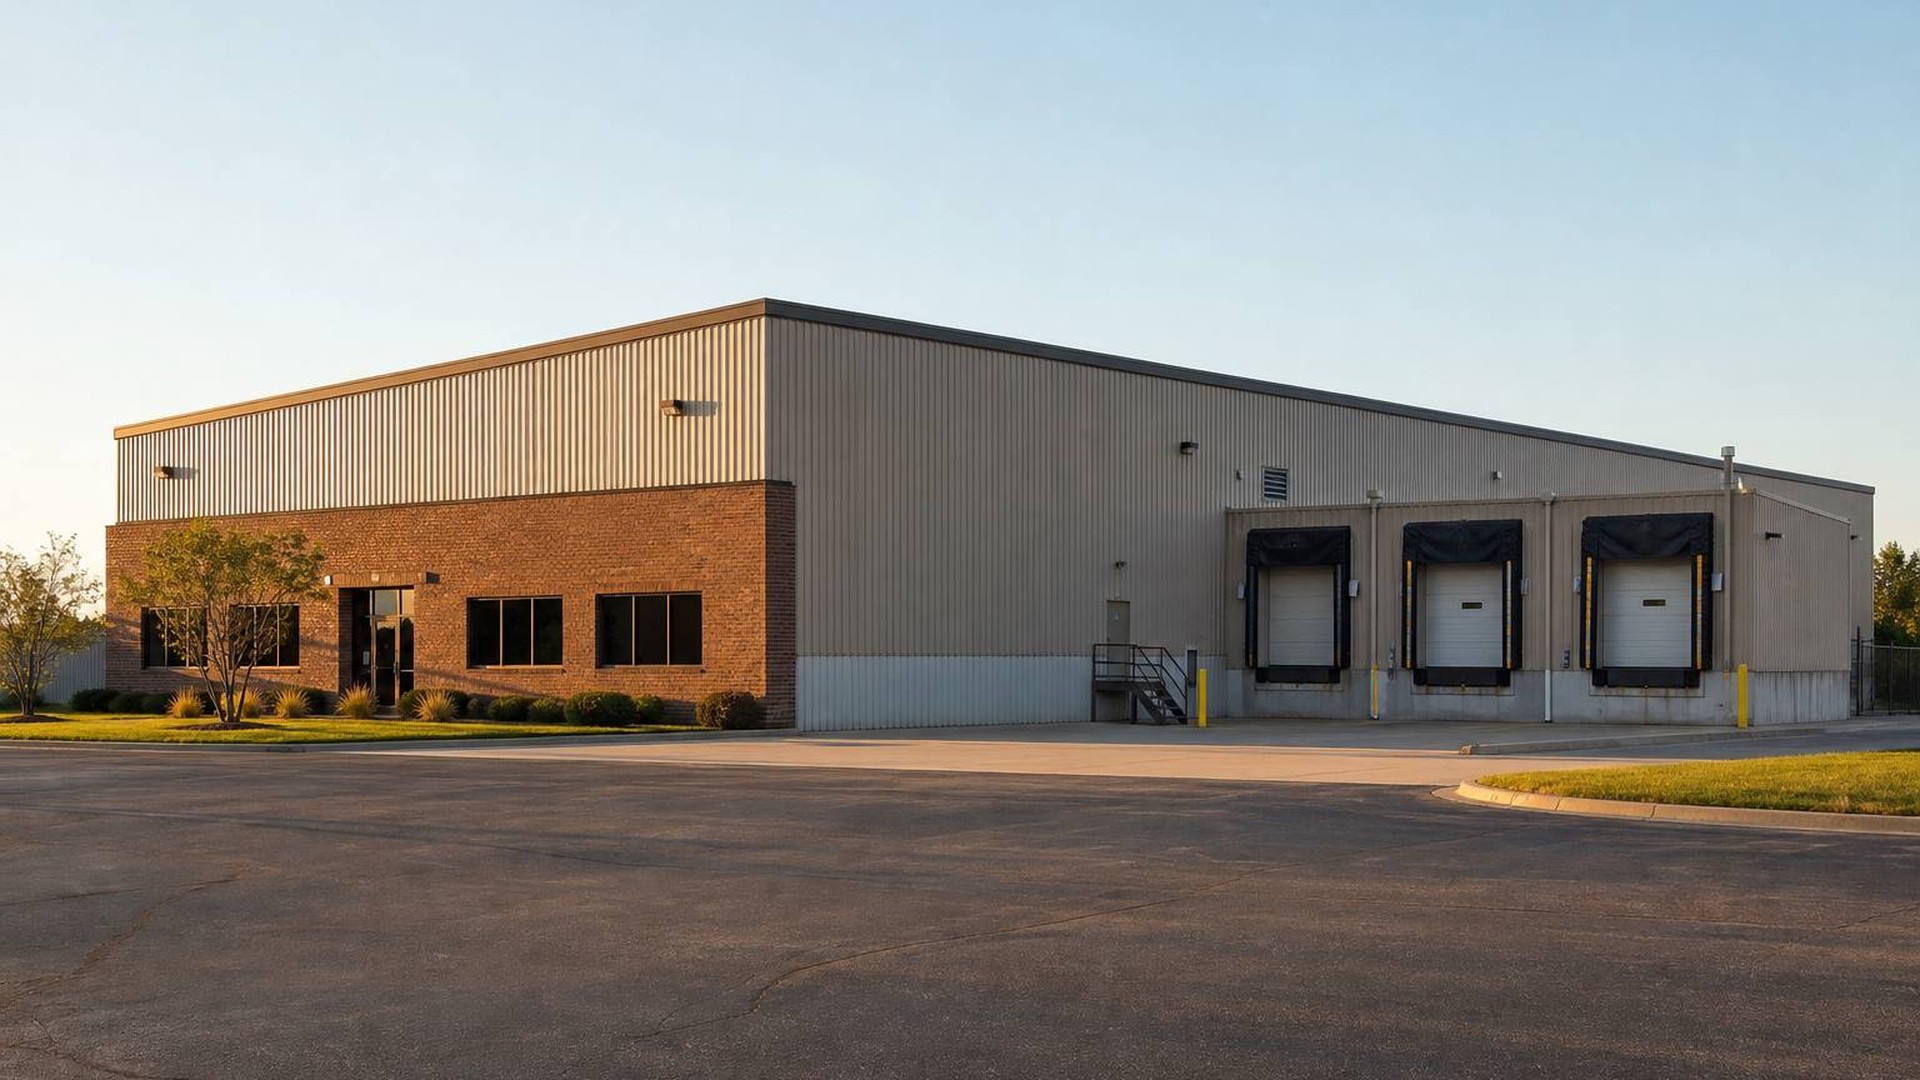
Commercial property cover turns on two things that are easy to get wrong: whether you are insured for replacement cost or depreciated value, and whether the limit reflects today’s construction prices. Underinsurance triggers a coinsurance penalty that reduces every claim, not just total losses.
Questions
If you insure for less than the stated percentage of value — commonly 80 or 90 per cent — the carrier reduces every claim in the same proportion. Carrying an accurate limit, or buying agreed value, removes it.
No. Flood and earth movement are excluded from standard commercial property forms and are written separately.
Often taken together
Property and general liability bundled into one policy for small and mid-sized firms.
Read more →
Third-party injury, property damage and advertising injury claims against your business.
Read more →Tell us what you already have and we will show you where this fits — or tell you plainly that you do not need it.